Please do your own research and check local sources. This is not legal advice.
Utah's real estate market continues to stabilize after pandemic-era surges.
This shifting dynamic offers a valuable backdrop for comparing land and residential real estate performance.
1. Tangibility & Simplicity
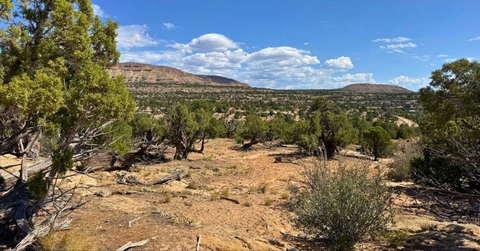
Land is easier to understand as an asset—raw, finite, and not subject to depreciation from wear and tear.
2. Unique Utility
Depending on location and zoning, land supports a cabin, RV, farming, recreation, or speculative investment—its versatility adds resilience.
3. Appreciation Drivers Differ
Land value is largely driven by scarcity, amenities like water rights or access, and long-term regional growth—not tied to home construction cycles or renovation trends.
1. Built-In Demand
Utah's strong economy, population growth, and job creation continue to fuel demand for housing.Steadily+1Redfin+3Rentastic+3Best Utah Real Estate+3
2. Leverage & Financing
Mortgages for homes are easier to obtain and often have lower rates than land loans, improving affordability and resale markets.
3. Income Potential
Homes can generate rental income through long-term leases or short-term rentals—land typically can’t without development.
When comparing asset complexity, land is simpler. Raw land has no structures to maintain and supply is inherently limited. Homes, however, can depreciate over time and require ongoing maintenance, which affects their long-term value.
Looking at appreciation drivers, land values are tied to scarcity, zoning rules, water rights, and future development potential. Homes, on the other hand, appreciate through housing demand, rental income potential, and upgrades or remodels that add value.
In terms of liquidity, homes tend to sell faster because there’s a larger pool of buyers and more accessible financing. Land sales, especially in rural counties, can take longer to close due to fewer active buyers.
For income potential, homes have an advantage. They can generate revenue through long-term rentals or short-term vacation stays. Raw land generally can’t produce income unless it’s developed or leased for specific uses like farming or recreation.
Finally, financing options differ significantly. Homes benefit from widely available mortgages with lower rates and flexible terms. Land financing is more limited, usually requires larger down payments, and often comes with higher interest rates.
Which appreciates more: land or homes?
It depends. Land can appreciate faster in high-demand rural or scenic areas. Homes hold consistent value due to higher turnover and rental demand.
Is land a better hedge against inflation?
Yes—land is durable and typically limited in supply, making it a good long-term hedge.
Is it harder to finance land than a home?
Yes—land loans are rarer, carry higher interest, and often require larger down payments.
Does land generate income?
Only if developed (e.g., leased for agriculture or recreation). Homes can be rented right away.
Choosing between land and homes depends on your goals:
In 2025’s Utah market, both asset types show strength but in different ways.